

The Ghana cedi suffered the steepest decline among all African currencies during the second quarter of 2026.
Data from the World Bank’s October Africa Economic Update shows that the currency depreciated by nearly 10 percent against the United States dollar between March and June. The report highlights that broader regional depreciation stemmed directly from escalating conflicts in the Middle East.
Regional currencies experienced immediate downward trends following heightened geopolitical tensions. The Lesotho loti, Namibian dollar, South African rand and Swazi lilangeni each dropped by more than 6 percent.
The World Bank noted the initial market reaction in its findings.
“Most countries with available daily exchange rate data recorded currency depreciations during the second quarter of 2026 relative to end-February, before the conflict intensified,” the organisation stated.
“In seven of the 22 countries monitored, excluding the CFA franc zone, the maximum depreciation exceeded 5.0%, including in the Democratic Republic of Congo, Ghana, the Seychelles, and South Africa.”
Market conditions stabilised heading into the late summer months.
“By end-August, however, much of this pressure had eased, with only 10 currencies remaining weaker than their end-February levels,” the report added.
Economic vulnerabilities and external shocks
Several structural factors worsened the impact of international turmoil on developing economies. Surging oil and energy costs expanded import bills for net energy-importing nations. This dynamic accelerated demand for US dollars, depleted foreign reserves and accelerated local currency depreciation.
Geopolitical instability drove global investors towards safer assets. Capital left frontier and emerging markets as risk aversion took hold worldwide.
Supply chain bottlenecks in the Middle East also raised prices for essential farming supplies, notably fertilisers. This disruption accelerated imported inflation across vulnerable regions.
Weaker exchange rates compounded fiscal strains for nations managing substantial foreign debt. Higher conversion rates raised the domestic cost of servicing US dollar-denominated obligations.
Recent market movements and cross-rate dynamics
Foreign exchange trading data demonstrates ongoing pressure on the cedi. The currency extended its total year-to-date decline against the dollar past 10 percent in recent weeks.
Interbank figures show the cedi traded at GH¢11.62 per dollar following a weekly decline of nearly 1.4 percent. Performance against other major foreign currencies presented a mixed picture during the same period.
The local currency gained ground against the British pound and the euro in wholesale trading channels, reaching GH¢15.40 and GH¢13.24 respectively.
Retail foreign exchange markets mirrored these mixed trends. The cedi strengthened slightly against both the dollar and the euro at retail counters, changing hands at GH¢11.93 and GH¢13.73 respectively.
Losses persisted against the pound in retail transactions, with the exchange rate settling at GH¢15.88.
Macroeconomic resilience and growth outlook in Ghana
In tandem with its currency findings, the World Bank’s October 2026 update maintains Ghana’s economic growth projection at 4.8 percent for the year.
This steady projection underscores resilient domestic activity, rapid disinflation and positive investor sentiment, reinforced by recent progress in the nation’s debt restructuring framework.
Analysts across West Africa note that while foreign exchange pressures demand cautious monetary policy management, baseline growth indicators continue to demonstrate underlying structural resilience.
Global economic resilience and policy imperatives
Beyond immediate exchange rate volatility, the broader macroeconomic landscape underscores a delicate balancing act for emerging markets.
Balanced macroeconomic management and structural resilience remain vital as developing nations navigate external shocks and tightening global financial conditions.
Business News of Wednesday, 7 October 2026
Source: gbcghanaonline.com
Ghana's cedi was Africa's worst-performing currency in Q2 of 2026 – World Bank
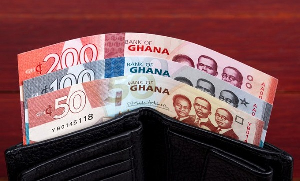 File photo of Ghana cedi notes


Entertainment