
This blog is managed by the content creator and not GhanaWeb, its affiliates, or employees. Advertising on this blog requires a minimum of GH₵50 a week. Contact the blog owner with any queries.
IM Akademy Blog of Friday, 30 October 2026
Source: Mustapha Ibrahim
Beyond the Balance Sheet: How Farihan Alhassan Is Redefining Banking Leadership in Africa
- Share:


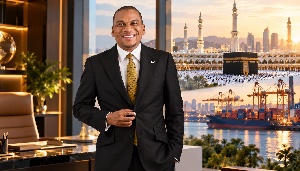
Africa needs leaders who do more than occupy prestigious offices. It needs individuals who understand that leadership is ultimately about identifying problems, creating solutions and building institutions that improve people's lives.
One such leader whose work deserves greater recognition is Mr. Farihan Alhassan, Managing Director of GCB Bank PLC.
Since assuming leadership of one of Ghana's most prominent indigenous banks in February 2025, Mr. Alhassan has overseen significant financial growth, introduced customer-focused innovations and strengthened the bank's engagement with international financial markets.
What makes his leadership particularly interesting is not simply the financial performance of GCB Bank, but the practical thinking behind some of its emerging initiatives.
Sometimes, the most remarkable innovations are not the ones that attract the loudest applause. They are the ones that quietly remove obstacles from people's lives.
Understanding People Beyond Their Bank Accounts
One initiative that particularly caught my attention is GCB Bank's dedicated Hajj Account.
For millions of Muslims worldwide, performing Hajj is a deeply cherished spiritual aspiration. In Ghana, many prospective pilgrims spend years saving towards this important religious obligation.
Recognising this need, GCB introduced a savings solution designed to help customers prepare financially for the pilgrimage.
With an initial deposit as low as GH¢50, flexible contributions and no monthly account maintenance charges, the product offers an accessible way for prospective pilgrims to plan towards their journey.
To some, this may appear to be just another banking product.
But I see something much bigger.
I see a financial institution recognising that customers are human beings with cultural identities, religious obligations, personal ambitions and unique financial needs.
This is the kind of thinking African institutions need.
True innovation is not always about introducing sophisticated technology. Sometimes, it is about understanding a problem that others have overlooked.
The Hajj Account represents an important lesson in customer-centred leadership: when institutions understand the communities they serve, they can create solutions that go beyond conventional commercial transactions.
Connecting Ghanaian Businesses to China
Another development worth highlighting is GCB Bank's October 2026 partnership with UnionPay International to introduce Renminbi-denominated debit and prepaid cards.
This initiative is particularly significant for Ghanaian entrepreneurs who travel to China to purchase machinery, electronics, construction materials, textiles and other commercial products.
International payments can present considerable challenges for traders, especially when transactions involve multiple currency conversions and unfamiliar payment systems.
By developing payment solutions that facilitate transactions directly in Chinese currency, GCB is responding to the practical realities of international commerce.
Think about the Ghanaian entrepreneur travelling to Guangzhou to purchase equipment for a growing business.
Think about the importer who needs convenient access to funds while negotiating with suppliers.
Think about the small business owner whose profitability depends partly on efficient international transactions.
These are the people who stand to benefit from innovations that make cross-border payments more convenient.
What I find particularly commendable is the strategic thinking behind such initiatives.
Ghanaian businesses are increasingly connected to international markets. Our banks must therefore evolve to support those relationships.
The future of African banking cannot be limited to deposits, withdrawals and traditional lending.
Our financial institutions must become active partners in trade, industrialisation and economic transformation.
Financial Performance That Deserves Recognition
Of course, leadership must also be measured by results.
GCB Bank's reported financial performance for 2025 provides compelling evidence of institutional progress.
The bank recorded approximately GH¢3.2 billion in profit before tax, representing growth of about 67.4%.
Total assets reached approximately GH¢52.6 billion, while customer deposits increased to GH¢41.3 billion.
Its loan portfolio also expanded to approximately GH¢16.39 billion.
These figures represent significant financial achievements during Mr. Alhassan's first year as Managing Director.
Naturally, institutional success is the collective result of the work of the board, management, employees and wider economic conditions.
Nevertheless, the ability to maintain strategic direction, strengthen performance and pursue innovation simultaneously is an important responsibility of executive leadership.
For me, the bigger question is not simply how much profit a bank makes.
It is what that financial strength enables the bank to accomplish for businesses, communities and the national economy.
A financially stronger bank has greater potential to support entrepreneurs, finance productive sectors and contribute to long-term development.
A Bank That Wants Businesses to Succeed
One of Mr. Alhassan's public statements about banking particularly resonates with my understanding of leadership.
He has argued that banks should not measure their success solely by profitability, but also by the lives they touch and the businesses they help grow.
This philosophy deserves serious attention.
Across Africa, thousands of promising businesses struggle to access financing, not necessarily because their ideas lack potential, but because they may lack the structures, records or financial capacity required by conventional lending systems.
A forward-thinking bank should do more than reject applications.
Where commercially appropriate, it should help businesses understand their weaknesses, improve their financial readiness and become stronger enterprises.
Mr. Alhassan has also emphasised the importance of supporting agriculture, manufacturing and other productive sectors of Ghana's economy.
These priorities are particularly relevant at a time when African countries are seeking to strengthen domestic production, create employment and reduce excessive dependence on imports.
Africa does not merely need banks that are profitable.
It needs profitable banks that help build profitable African businesses.
Thinking Beyond Ghana's Borders
Another noteworthy aspect of GCB's strategic direction is its engagement with the Pan-African Payment and Settlement System, PAPSS.
This initiative seeks to make cross-border payments among African countries more efficient, including through local-currency settlement.
GCB was an early participant in this continental payment transformation, becoming the first financial institution to successfully process a live PAPSS transaction before Mr. Alhassan's appointment.
Under his leadership, the bank has continued engagements aimed at strengthening African financial integration.
In May 2026, he led a delegation to Cairo for discussions involving Afreximbank and PAPSS.
These engagements reflect an important reality: the future of African economic development will depend partly on how effectively African countries trade with one another.
We cannot speak seriously about continental economic integration while ignoring the financial infrastructure required to make it possible.
African banks have an important role to play in building that infrastructure.
From Ghana to International Recognition
Mr. Alhassan's professional journey is equally inspiring.
Before becoming Managing Director of GCB Bank, he accumulated extensive banking experience through leadership positions at institutions including Barclays Bank, now Absa, and Stanbic Bank Ghana.
His career reflects years of professional development, executive responsibility and exposure to international banking practices.
In July 2026, he received the Special African Leadership Commendation Award at the African Business Leadership Awards in London.
He was also appointed to the Mastercard Africa Leadership Council, becoming its first Ghanaian member.
These milestones are significant because African executives deserve opportunities not only to participate in global financial conversations, but also to contribute to shaping them.
The continent possesses exceptional professional talent. What we need are more platforms, institutions and opportunities through which that talent can influence international decisions.
What Young African Leaders Can Learn
As someone deeply involved in leadership development, public speaking and professional training, I find several important lessons in Mr. Alhassan's approach.
First, leadership begins with understanding people.
The Hajj Account demonstrates how institutions can develop products around the actual needs of their customers.
Second, innovation should solve practical problems.
The China payment initiative shows the importance of designing financial services around real commercial activities.
Third, leadership requires both vision and measurable performance.
Ideas are important, but sustainable institutions also need financial discipline, operational excellence and accountability.
Fourth, African leaders must think globally while remaining responsive to local realities.
International exposure becomes truly valuable when it helps strengthen institutions and expand opportunities at home.
Finally, leadership should create possibilities for others.
The ultimate value of a successful bank is not confined to its financial statements. It also lies in the businesses it supports, the jobs it helps sustain and the communities it serves.
A Leadership Example Worth Celebrating
We sometimes wait until African professionals receive international recognition before appreciating the value of their work.
Yet across our continent, individuals are making important contributions through innovation, institutional development and practical problem-solving.
Mr. Farihan Alhassan's leadership at GCB Bank offers one such example.
His tenure is still unfolding, and the long-term impact of many initiatives will depend on effective implementation and sustained results.
However, the progress recorded so far, together with the bank's evolving approach to customer needs, international payments and enterprise development, provides meaningful reasons for recognition.
I believe we should celebrate African leaders not merely because they hold influential positions, but because of the ideas they introduce, the institutions they strengthen and the opportunities they help create.
The greatest achievement of a leader is not the position they occupy, but the positive difference their leadership makes in the lives of others.
For Mr. Farihan Alhassan, the opportunity is to continue building a bank whose success is reflected not only in billions of cedis, but also in the ambitions of Ghanaian entrepreneurs, the aspirations of ordinary customers and the future of African commerce.
That is a vision of banking leadership worth recognising.
And that is the kind of leadership Africa needs more of.
By Ibrahim Mustapha
Communication Consultant | Leadership Trainer
CEO, Public Speaking Factory