

Ghana’s financial markets exhibited a mixed response to the government’s 2027 Budget Statement and Economic Policy on Friday, November 13, the first trading day following its presentation to Parliament by Finance Minister Dr Cassiel Ato Forson.
Investors were confronted with a fiscal programme that seeks to consolidate macroeconomic stability while accelerating productive-sector investment, import substitution, export development and employment creation under the government’s four-year New Economy agenda.
The immediate market considerations included the implications of the proposed fiscal deficit and domestic financing requirements for interest rates, the cedi, government securities and equities, as well as the government’s announcement that it would repay GH¢29 billion of Domestic Debt Exchange Programme (DDEP) bonds ahead of their February 2027 maturity.
The government also announced plans to settle a US$590 million Eurobond obligation due in January 2027 before the end of December this year.
These debt repayment commitments were particularly important to investors because they provided assurances about near-term liquidity and the government’s ability to meet obligations without resorting to another debt restructuring.
The available Friday trading indicators point to a market that was absorbing the budget’s implications rather than immediately making a decisive reassessment of Ghanaian assets.
The Ghana Stock Exchange closed lower on Friday last week, with the GSE Composite Index (GSE-CI) falling 36.03 points to settle at 13,960.40. The GSE Financial Stocks Index (GSE-FSI) also dipped 36.01 points to close at 7,148.52, with total session volume reaching 1,654,749 shares.
MTN Ghana, which accounted for approximately 84 per cent of October’s equity trading value, gained marginally to GH¢6.62 a slight daily gain of +0.15%.
Total reported trading volume was approximately 1.48 million shares. Market capitalization remained around GH¢263.03 billion.
The Ghana Fixed Income Market (GFIM) was arguably the most immediately important market for assessing the budget’s implications because of its sensitivity to government financing requirements and debt management operations.
On Thursday, November 12, GFIM recorded GH¢3.08 billion in trading volume across 317 transactions driven heavily by the announcement of an early redemption/buyback offer for GH¢29 billion in domestic bonds maturing in February 2027 which consequently recorded GH¢411.12 million in combined outright and sell/buy-back transactions. Its outright yield declined from 11.20 per cent at the opening to 11.07 per cent at the close, suggesting some immediate demand for the instrument.
Treasury bills accounted for GH¢1.46 billion, while DDEP bonds contributed GH¢1.30 billion. Government bond sell/buy-back transactions accounted for another GH¢321.35 million.
For institutional investors, the government’s announcement that GH¢29 billion was available in the Cedi Sinking Fund to redeem the February 2027 principal was an important development.
It reduced uncertainty over the immediate repayment of that particular obligation, although investors would still need to consider the implications of the government’s wider borrowing programme for future yields and liquidity.
The foreign-exchange market presented a less comfortable picture.
The Bank of Ghana’s latest available interbank reference rate before Friday’s market assessment was GH¢11.71 to the US dollar on November 12, compared with GH¢11.66 a week earlier.
This represented a depreciation of approximately 0.43 per cent over the week.
Reuters had also reported that corporate demand for foreign currency, particularly from the services and commercial sectors, was continuing to exceed supply.
The market’s principal concern was whether the government’sincreased investment ambitions and associated import requirements could generate additional foreign-exchange demand before the expected expansion in domestic production and exports began generating compensating foreign-currency receipts.
The government’s commitment to settle its US$590 million January 2027 Eurobond obligation before the end of December was potentially reassuring, given the implications for external debt servicing and foreign-exchange availability.
However, no independently verified Friday interbank dollar turnover or closing weighted-average exchange rate was available to establish the immediate post-budget response.
Similarly, comparable Friday interbank funds-market transaction volumes and weighted-average lending rates were not available.
The Bank of Ghana’s 14 per cent monetary policy rate therefore remained the principal established policy reference, rather than evidence of a new market-driven movement in short-term funding costs.
Following the presentation of the 2027 Budget Statement, Ghana’s sovereign Eurobonds traded relatively unchanged by the morning of Friday, November 13, 2026. International dollar-denominated sovereign Eurobonds held steady with minimal movement in terms of trading prices and yields.
Analysts noted that the lack of sharp negative or positive volatility was anchored by key announcements in the budget speech—particularly the government’s plan to settle a US$590 million Eurobond obligation ahead of its January 2, 2027 maturity date, alongside a medium-term strategy ruling out new Eurobond issuances from 2027 through 2030 in favor of domestic financing.
International investors will particularly welcome the government’s intention to settle the US$590 million January obligation ahead of maturity, although the implications for the dollar sinking fund and other external debt commitments will remain important considerations.
Overall, the available evidence suggests that Ghana entered the first post-budget trading session without an immediately demonstrable broad-based reassessment of its financial assets.
The central issue for investors remains whether the government’s New Economy investment programme can accelerate productive capacity and employment without reviving the fiscal, interest-rate and exchange-rate pressures that contributed to Ghana’s recent debt crisis.
For now, the government’s debt repayment assurances provide an important confidence-building signal. Its financing discipline and ability to deliver the promised economic transformation will determine whether that confidence becomes sustained investment.
Business News of Wednesday, 18 November 2026
Source: economytimesnews.com
Ghana stock market falls as cedi weakens after 2027 budget presentation
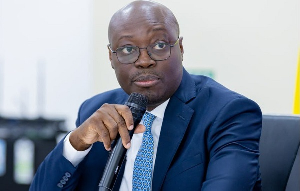 Dr Cassiel Ato Forson is the Minister of Finance