

The cedi lost 3.9 per cent of its value against the US dollar in September, wiping out most of its August gains and pushing its losses for the year past 10 per cent. Rising US interest rates, oil prices above US$100 a barrel, softer gold prices and a shrinking reserve cushion now threaten to deepen the pressure through the festive season, raising the risk that inflation picks up again.
Bank of Ghana interbank data show the cedi closed September at GH¢11.7159 to the dollar, from GH¢11.2556 at the end of August. It also weakened 1.8 per cent against the British pound, to GH¢15.5376, and 1.6 per cent against the euro, to GH¢13.2845.
The currency held steady at the start of October, trading at GH¢11.7159 to the dollar on Friday, October 2, unchanged from its September close.
For a business importing goods worth US$10,000, September’s slide means paying about GH¢4,600 more than at the start of the month. At the forex bureaus, where households and small traders buy foreign currency, the dollar sold at an average of GH¢12.15 on October 1.
Databank Research puts the cedi’s year-to-date depreciation at 10.04 per cent as of late September, before a further decline in the final days of the month.
The pattern suggests the possibility of a reversal from last year, when the cedi rallied in the final quarter. In October 2025, the currency strengthened from GH¢12.63 to GH¢11.21 to the dollar in a single fuel pricing window, an 11.2 per cent gain that nearly erased its third-quarter losses.
Databank attributed September’s weakness to sustained demand for dollars from the energy and manufacturing sectors, against relatively tight supply on the interbank market. That pressure persisted even though the Bank of Ghana injected about US$445 million in forex support into the market in September, against a target of US$500 million.
“Looking ahead, we expect the cedi to maintain a mild depreciation bias as seasonal FX demand builds into the festive period,” Databank Research said.
The festive demand is only one of several pressures converging on the currency in the final quarter.
The US Federal Reserve raised its policy rate by 25 basis points to 4.0 per cent in September, after a string of stronger-than-expected inflation readings in the United States. Markets are already pricing in a further increase in December, and JP Morgan, a leading investment bank, forecasts another quarter-point hike before the end of the year.
Higher US rates strengthen the dollar and draw investment away from emerging markets. Databank said the Fed’s move and the dollar’sstrength that followed added to the cedi’s losses in September. Members of the Bank of Ghana’s Monetary Policy Committee (MPC) warned that tighter global conditions “could trigger portfolio outflows and pressure emerging market currencies.”
Another pressure is oil. Brent crude traded at about US$102 a barrel on Friday last week, up roughly seven per cent in a month and nearly 60 per cent higher than a year ago. Prices have been pushed up by fresh US military deployments to the Middle East, signals from Washington that strikes on Iran could resume after the November US midterm elections, and China’s decision to halt most refined fuel exports for October. A recovery in Gulf crude exports and a G7 plan to release up to 100 million barrels of emergency stocks have kept prices from climbing further.
Because Ghana imports most of its refined fuel, every rise in crude prices increases the country’s dollar bill. One MPC member said the pressure was already visible in “rising petroleum-related import bills observed at the foreign exchange auctions.”
Consumers are feeling it at the pump. Fuel prices in Ghana have risen by more than 33 per cent since the start of the year, according to JoyNews Research. The government has absorbed GH¢2 per litre of the diesel price to cushion consumers, but the International Monetary Fund has warned that such subsidies must be temporary and well-targeted to avoid fiscal damage.
The third pressure is the country’s shrinking buffer. Gross international reserves hit a record US$14.5 billion in February, equivalent to six months of import cover. By the end of August, they had fallen to about US$11.1 billion, or 4.2 months of cover. They recovered to US$12.0 billion by September 22, but remain well below their peak.
This leaves Ghana far from its own target. Under the Ghana Accelerated National Reserve Accumulation Policy, passed by Parliament in February, reserves were projected to reach 8.6 months of import cover by the end of 2026.
At the MPC meeting on September 23, Governor Dr Johnson Pandit Asiama warned that the decline in reserves, a weaker current account and a pause in GoldBod’s gold exports from mid-August “call for a careful look at our buffers ahead of the usual rise in foreign exchange demand in the fourth quarter.”
“Rebuilding net foreign assets must therefore remain the priority heading into the fourth quarter,” the Governor said.
Gold, which has underpinned the cedi’s stability, is also losing momentum. Although gold export earnings were 32.9 per cent higher in the first eight months of the year, prices have broadly declined since March. Gold traded at about US$4,140 an ounce on Friday last week, well below the US$5,000 average GoldBod used to set its 2026 targets.
Governor Asiama linked the decline directly to US monetary policy. “When the US increases its policy rate, gold prices tend to be depressed,” he said.
The impact is visible in the Bank’s own gold holdings. Ghana held more gold in August than in June, 25.2 tonnes against 24.4 tonnes, yet its value fell from US$3.652 billion to US$3.565 billion. The Governor said the pause in GoldBod’s exports, together with higher service payments, was expected to push the current account into deficit in the third quarter, though GoldBod has since resumed significant shipments.
The Governor also flagged domestic pressures. Government spending is set to rise, the share of short-term domestic debt is increasing, and completion of the external debt restructuring will raise debt service obligations. Each, he said, carries implications for liquidity and the exchange rate.
The central bank is leaning on gold to respond. Since August, GoldBod has channeled its gold earnings directly into the foreign exchange market under a new financing model. In August, it sold US$668 million to commercial banks and made US$647 million available to the Bank of Ghana for reserves. The Governor has said he wants GoldBod to play a bigger role in supplying dollars to the market.
Remittances offer some further cushion. Inflows from Ghanaians abroad totalled US$3.65 billion in the first half of the year, marginally lower than a year earlier, and typically rise during the festive season.
By conventional standards, Ghana’s buffers remain adequate. Import cover of more than four months sits above the three-month benchmark commonly used to judge reserve adequacy. But the pace of the decline, softer gold prices and a projected fall in cocoa output, have narrowed the central bank’s room to defend the cedi if pressure intensifies.
That is the bigger risk for households and businesses. Currency stability has been one of the main forces behind Ghana’s sharp fall in inflation over the past two years. In July, imported inflation fell to 2.0 per cent, helped by a stable exchange rate.
The support is now fading. Headline inflation rose to 5.0 per cent in August from 4.6 per cent in July, driven mainly by non-food items such as transport and housing. One MPC member noted that inflation has climbed from a March low of 3.2 per cent, “a cumulative increase of 1.8 percentage points in five months.”
Beyond the cedi, the MPC listed further upside risks to prices: quarterly utility tariff adjustments, higher petroleum prices, expected transport fare increases and a strong El Niño that could hit food harvests. Good harvests, the diesel subsidy and continued fiscal discipline are the main factors that could hold prices down.
September inflation figures are due from the Ghana Statistical Service this week. Fitch Solutions projects inflation will rise to nine per cent by the end of 2026, driven largely by renewed pressure on the cedi, which would be within but towards the upper half of the Bank of Ghana’s target band of eight per cent, plus or minus two percentage points.
Business News of Tuesday, 6 October 2026
Source: economytimesnews.com
Cedi exchange rate pressure raises inflation risk
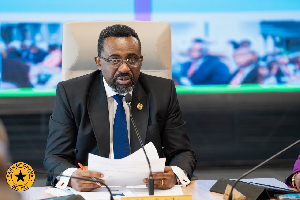 Dr Johnson Asiama is the Governor of BoG


Entertainment